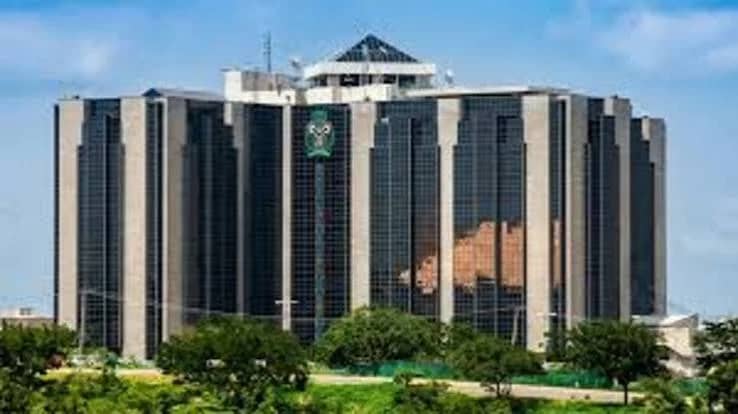
The Central Bank of Nigeria’s decision to cut its benchmark interest rate to 23 per cent is expected to put further pressure on yields across the fixed-income market as investors adjust to a lower interest-rate environment.
The Monetary Policy Committee reduced the Monetary Policy Rate by 350 basis points from 26.5 per cent at its 307th meeting in Abuja on Tuesday.
The decision came amid moderating inflation. Headline inflation eased to 15.39 per cent in August from 15.43 per cent in July, while food inflation declined to 19.57 per cent from 20.31 per cent, according to the National Bureau of Statistics.
Fixed-income yields had already started declining ahead of the MPC decision, reflecting changing market expectations.
At its latest Open Market Operations auction, the CBN offered N1tn in bills, attracting N6.31tn in subscriptions and allotting about N4.4tn.
The 154-day OMO bill cleared at 18.41 per cent, while demand reached N4.2tn against an offer of N400bn. Its true yield stood at 19.96 per cent, down from 20.64 per cent at the previous auction.
The latest reduction in the MPR could reinforce the downward repricing of fixed-income securities as investors adjust their return expectations to the lower policy-rate environment.
Treasury bills and OMO bills are likely to respond more quickly because their yields are closely linked to short-term liquidity conditions and monetary policy.
The adjustment in the bond market could be slower and will depend on factors including inflation expectations, market liquidity and the government’s borrowing requirements.
For investors holding existing fixed-income securities, particularly longer-duration bonds, falling yields could translate into price gains. This is because securities carrying higher coupons may become more attractive relative to newly issued instruments with lower yields.
However, investors putting fresh money into the market could face lower returns if new Treasury bills, OMO bills and bonds are issued at reduced rates.
Analysts also expect some investors seeking higher returns to consider other asset classes, including equities, corporate debt and longer-dated securities, if short-term fixed-income yields continue to decline.